A rule that has always applied to Americans
Greece designates certain regions and islands as border areas. In those places, a buyer who is not a national of an EU or EFTA country needs prior approval from the Greek State before acquiring a property or a right over it. The framework is Articles 24 to 26 of Law 1892/1990, amended several times since, and it exists for national security reasons rather than as a housing or tax measure.
For British buyers this became news in 2021, when Brexit moved them into the category the rule covers. For US citizens nothing changed, because an American buyer has always been outside the EU for this purpose. The rule does not name the United States, and it is not aimed at American buyers. It simply applies to them by default, the same way the Schengen 90/180 visitor rule does.
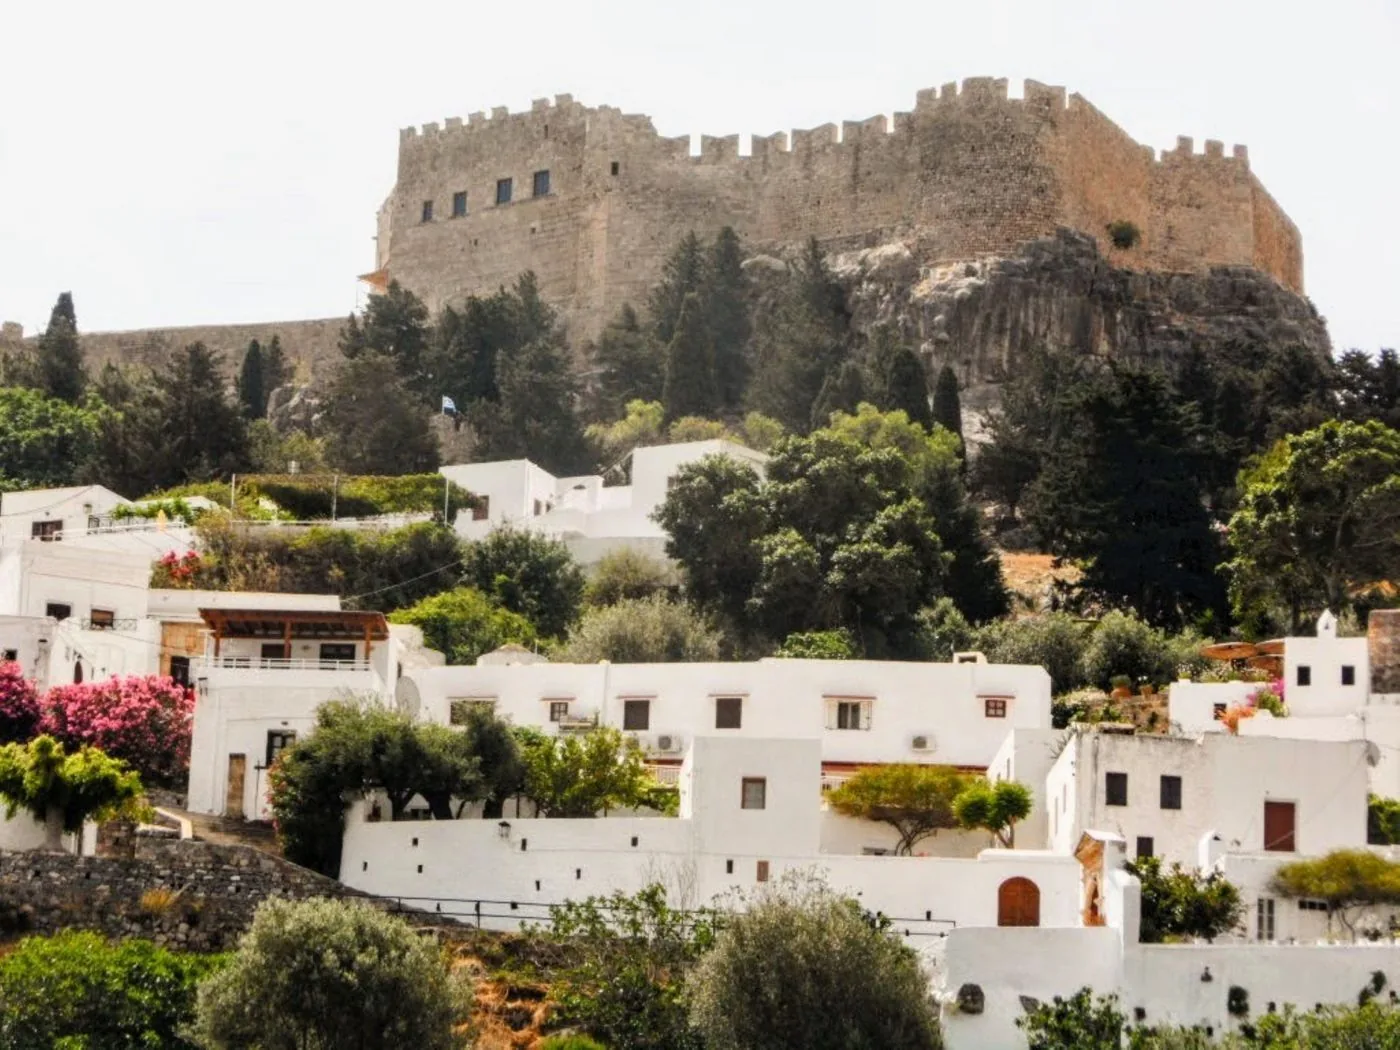
The practical point is that this is a question about the specific property, not about you. A US buyer purchasing on Crete's north coast or in the Cyclades outside Santorini will usually never meet it. The same buyer choosing a village house on Rhodes will.
Where the designation actually applies
The list of border areas in Article 24, as replaced in 2014, covers the regional units of the Dodecanese, Evros, Thesprotia, Kastoria, Kilkis, Lesvos, Xanthi, Preveza, Rodopi, Samos, Florina and Chios, the islands of Thira and Skyros, several former provinces in the north including Nevrokopi, Pogoni, Konitsa, Almopia, Edessa and Sintiki, and the small islands of Othonoi, Mathraki and Erikoussa off Corfu.
Three consequences follow for the places US buyers look at most. The whole Dodecanese is in, which means Rhodes, Kos, Patmos, Symi, Karpathos and the rest of the group. Thira is Santorini, and it is named in the statutory text even though some buyer guides online describe Santorini as outside the zones; if you are working from our Santorini mortgage guide, add this step to the plan. And the Ionian picture is mixed: Corfu itself is not in the list, but Preveza and Thesprotia on the mainland opposite are, as are the three small islands to Corfu's north west.
Crete does not appear in the current list, although older designations and several commentaries still mention parts of it. That kind of discrepancy is exactly why the list should be treated as a starting point for a question, not as an answer. Designations have been revised over the years, and the only reliable check is a Greek lawyer confirming whether the specific parcel falls inside a designated area at the time you buy.
What needs approval, and what happens without it
The prohibition is wider than a straightforward purchase. It covers acquiring ownership, establishing other real rights over the property, and certain contractual rights such as longer leases. It also reaches transfers of shares in companies that hold property in a border area, which is why buying through a company is not a reliable way around it.
It applies to legal persons as well as individuals. A US LLC or other company with its seat outside the EU and EFTA is in the same position as a US citizen, so structuring the purchase through an American entity adds a step rather than removing one. If you are considering any ownership structure, take Greek and US advice on it together before the approval application is prepared, because the application is made in the name of whoever will actually acquire.
A transaction concluded without the required approval is treated as absolutely void under the law. In practice that means a Greek notary will not draw up the final contract without the approval in the file, so the realistic risk is not an illegal purchase slipping through. It is a purchase that stalls at the last step because nobody asked the question early enough.
How the approval process works
The application goes to a committee within the relevant Decentralised Administration, the regional arm of central government for the area where the property sits. The committee includes representatives of several ministries, and the representative of the Ministry of National Defence must vote in favour for the prohibition to be lifted. The application states who you are, what you intend to acquire and what you intend to use it for.
You do not need to travel for it. A Greek lawyer normally prepares and files the application under a power of attorney. Expect to supply a copy of your passport, your Greek tax number, a description of the property with its cadastral or topographical details, a statement of intended use, and in many cases a criminal record certificate and evidence of the source of funds. For a US applicant, the criminal record document is commonly an FBI Identity History Summary. Because that is a federal document, its apostille comes from the US Department of State rather than from a state Secretary of State, and it will need an official Greek translation.
On timing, published estimates range from about two to six months, and they vary by committee and by season. Treat any single number you are quoted as a best case. Applications from private buyers purchasing a home for their own use are commonly reported as approved, but no lawyer can guarantee the outcome in advance, and the plan should allow for that.
Why it sits on the mortgage's critical path
The approval has no effect on your borrowing terms. The loan-to-value ceiling Greek lenders apply to US residents, commonly in the 50 to 65 per cent range, and the shorter maximum terms are driven by where you live and earn, not by where the property is. Our guide to non-resident mortgages in Greece covers those terms in detail.
What the approval does affect is the timetable. A lender will not release funds into a purchase that cannot lawfully complete, so the drawdown waits for the committee. Mortgage offers carry expiry dates. If the approval arrives after the offer lapses, the likely consequence is not a refusal but a revalidation: fresh pay stubs or tax returns, fresh bank statements, sometimes a fresh valuation, and possibly a different rate if the market has moved.
The fix is sequencing. The Greek tax number, the AFM, and a Greek bank account both take time to arrange from the United States, and both are needed anyway. The border area check costs nothing to run alongside them at the very start. The documents a Greek lender asks for overlap heavily with what the committee wants, so gathering and apostilling them once, for both purposes, saves weeks.
Protecting your deposit in the preliminary agreement
Many Greek purchases run through a preliminary agreement with a deposit, and in Greek practice a buyer who withdraws can forfeit it. That is the wrong structure to sign while an approval you do not control is still pending.
The answer is not to avoid the preliminary agreement but to have your lawyer draft it with the border area approval and the mortgage offer as conditions rather than assumptions. What happens to the deposit if approval is refused, and what happens if it is merely slow, are two separate questions, and both belong in the document. Sellers and agents in designated areas deal with non-EU buyers regularly, so this is a normal request. Our guide to the preliminary agreement and mortgage finance covers the wider drafting points.
One timing pressure deserves a specific warning this autumn. On 6 September 2026 the Greek government announced a plan to raise the property transfer tax for buyers from outside the EU from 3 per cent to 15 per cent. At the time of writing no bill has been published, reported start dates differ, and the scope and exemptions are still unconfirmed. It is reasonable to ask your lawyer how a change in transfer tax would be handled in the contract. It is not a reason to sign a preliminary agreement on a compressed timetable to beat a date that does not yet exist in law, especially when the border area approval alone can take months.
Special cases for American buyers
A second citizenship can change the answer. The rule is aimed at buyers who are not EU or EFTA nationals, so an American who also holds, for example, Irish, Italian or Greek citizenship can generally buy under that citizenship without the approval step. The purchase then has to be made under that nationality, with the documents to match, which is a decision to make with your lawyer before the tax number is issued rather than after.
A residence permit does not work the same way. A Greek Golden Visa gives you the right to live in Greece, but it does not change your nationality, and it is not listed among the exemptions in the published commentary on the law. If you plan to buy a Golden Visa property on Rhodes or Santorini, budget time for both processes rather than assuming one covers the other.
Greek-Americans of Greek descent who do not hold Greek citizenship should ask specifically how their position is treated, rather than relying on family history or forum advice. And whatever the ownership outcome, owning property in a border area, approved or not, gives no additional right to spend time in Greece beyond the visitor rules that already apply to you.
Border area checks before you commit
- Whether the specific parcel falls inside a designated border area, confirmed by a Greek lawyer at shortlist stage.
- Which nationality the purchase will be made under, if you hold an EU or Greek passport as well as a US one.
- Whether any company or trust structure is involved, and whether it changes who must apply.
- Your AFM and Greek bank account, started at the same time as the approval question.
- Passport, FBI Identity History Summary and other US documents, apostilled at the right authority and officially translated.
- A power of attorney allowing your lawyer to file the application in Greece.
- A preliminary agreement that treats the approval and the mortgage offer as conditions, with deposit terms for refusal and for delay.
- Your mortgage offer's expiry date, and what revalidation would require if the committee is slow.
- How any change in transfer tax before completion would be handled in the contract.
Questions US buyers ask
Continue your Greek property research
This guide is general information, not personal financial, legal, tax or currency advice. The designation of Greek border areas and the approval procedure are set out in legislation that has been amended over time, and whether they apply to a particular property or buyer is a question for an independent Greek lawyer. The proposed change to transfer tax for non-EU buyers had not been legislated at the time of writing. Mortgage availability is subject to credit, income, valuation and lender criteria.